
Kenya’s inflation outlook remains precarious due to weather related risks associated with the looming El Nino rains. According to a Q 3 2026 Report by Standard Investment Bank(SIB), weather-related risks are becoming an increasingly important factor in Kenya’s inflation outlook.
Improved rainfall could support agricultural production and ease food-price pressures, but excessive rainfall and flooding could instead damage crops, disrupt transport networks and raise distribution costs.
These risks come alongside elevated energy prices and ongoing global uncertainty, creating a challenging environment for monetary policy.
Kenya’s headline inflation accelerated from 6.6% in August to 6.8% in September, remaining within the Central Bank of Kenya’s 2.5–7.5% target range. The increase was primarily driven by a sharp rise in core inflation, which climbed from 3.4% to 4.0%, alongside higher food inflation, which rose from 9.0% to 9.5%.
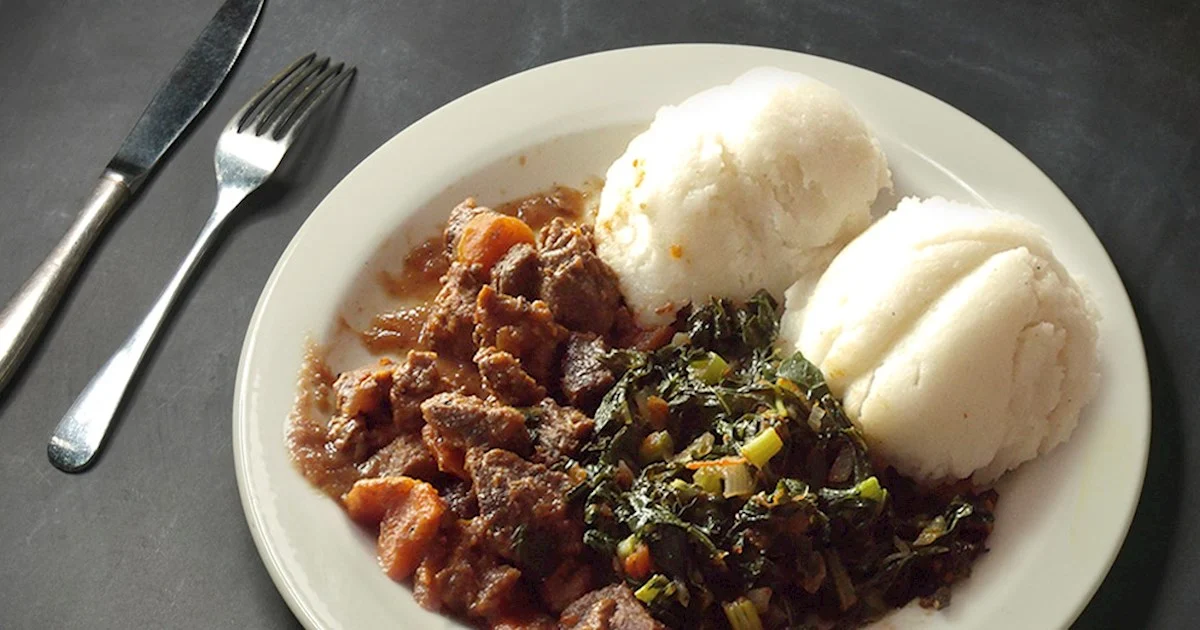
Persistent supply-side pressures, particularly from the ongoing dry spell, pushed up the prices of milk, beef and fresh produce, with potatoes, kale, cabbages and tomatoes recording notable annual increases.
Meanwhile, energy and transport costs remained elevated, with annual petrol and diesel prices rising by 15.8% and 26.9%, respectively, contributing to a 15.6% increase in the transport index.
For the fixed-income market, a renewed food or energy shock would complicate the disinflation process and could limit the scope for further yield compression.
While inflation remains within the CBK’s target range, higher food prices, weather-related supply disruptions and potential second-round effects remain key risks to monitor, particularly as the CBK balances the need to support economic growth against the risk of renewed inflationary pressures.
Despite a slight uptick in annual inflation rates in recent months, the metric remains below the mid-point of CBK’s target range of 5±2.5%.
The global inflation outlook has become more challenging as renewed disruptions to energy production and exports in the Middle East have pushed oil and gas prices higher, reversing some of the moderation seen earlier in the year.
The OECD estimates that headline inflation across the G20 is set to rise to 4.1% in 2026 from 3.4% in 2025, while more than half of G20 economies are currently recording inflation above their central banks’ targets.
The renewed energy shock is also feeding into business costs, particularly through higher fuel and refining costs, raising the risk of further second-round effects on consumer prices.
The impact is already becoming evident across major economies. In the euro area, headline inflation rose to 3.2% in August from 3.0% in July, with energy inflation increasing sharply to 14.3%, while core inflation remained broadly stable at 2.5%.
Meanwhile, U.S. headline inflation stood at 3.4% in August, with energy prices rising 16.3% y/y, highlighting the growing contribution of energy costs to overall price pressures. In Japan, energy inflation also turned positive for the first time since November 2025.
For emerging markets, the renewed energy shock presents a particularly important risk given the potential pass-through to transport, electricity, food production and imported goods.
While underlying inflation remains relatively contained in some economies, persistent energy costs could slow the disinflation process and limit the scope for monetary easing.
For Kenya, where higher fuel prices can quickly transmit through transport and production costs, the global energy environment remains an important external risk to the inflation outlook and domestic fixed-income market.







Leave a comment