
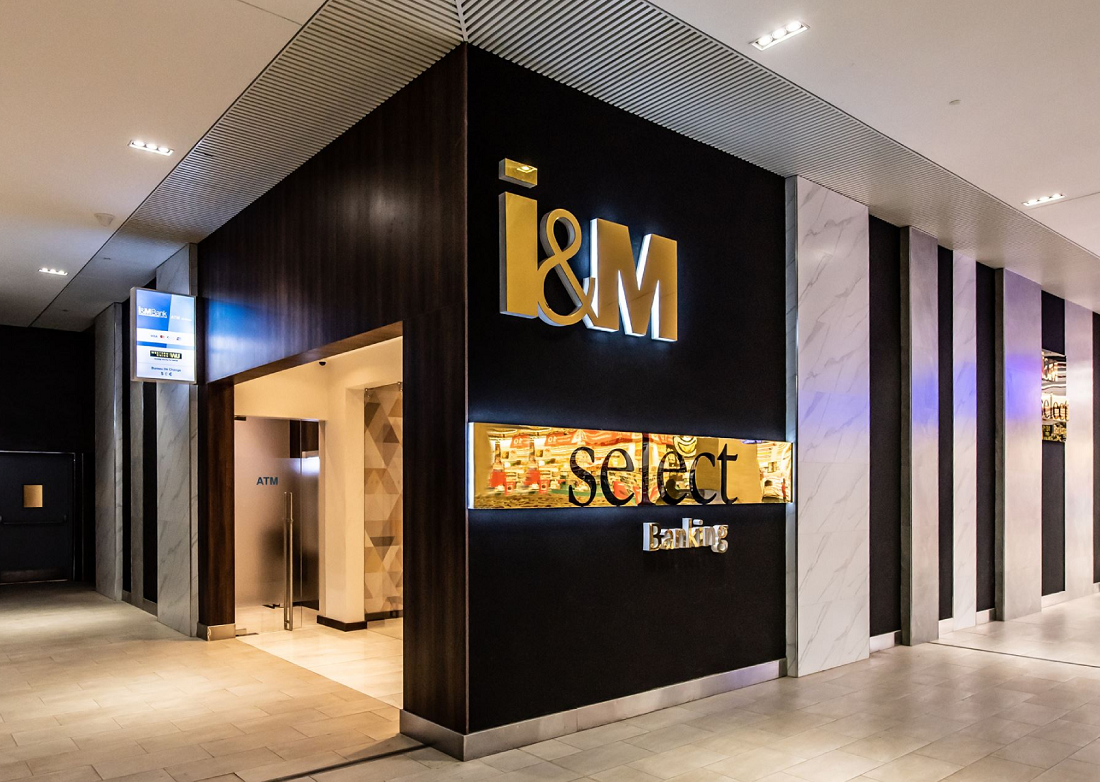
I&M Bank Kenya is currently issuing corporate bonds under a KSh 20 billion programme, with the first tranche targeting KSh 10 billion. In simple terms, this means investors are lending money to the bank, which will be used to support lending activities, strengthen its capital base and fund long-term business growth.
The I&M Bond has a fixed Coupon of 12.20% per annum with payments done semi-annually (twice a year) with a tenor of 5.5 years.
Interested investors are required to have a minimum investment of KSh 500,000 with an offer period of between 30th April to 15th May 2026 while expected listing at the Nairobi Securities Exchange(NSE) expected on 21st May 2026.
How returns on I&M Bond look like.
If one invests KSh 1,000,000, the Gross semi-annual interest is KSh 61,000 with a Net (after 15% tax) of KSh 51,850. This is equivalent to about KSh 8,600 – 8,700 per month. This is higher than typical money market fund yields, but with a key trade-off: Your money is locked in for 5.5 years, unlike Money Market Funds which are liquid.
About I&M Bank:
For the year ended December 2025, I&M reported a 29% growth in profit before tax, 23% increase in operating income and Customer deposits of KSh 349 billion with Net loan book of KSh 218 billion.
This reflects strong operational momentum, even in a high interest rate environment. The Bottom Line is that this bond may appeal to investors looking for predictable, fixed income with higher yields than short-term instruments.
The I&M Bond exposes investors to a stable banking institution However, risks to consider are liquidity constraints (5.5-year commitment). There is also an interest rate risk (rates could rise further).
I&M Bond. Worst Case Scenario. The risk is concentrated in two areas.
First, ability to pay: I&M Bank Kenya is a well-capitalized, profitable institution, so the probability of default is low, though not zero. You are effectively taking on bank credit risk, not sovereign risk.
Second, interest rate exposure: if market rates move above 12.2%, the bond becomes relatively less attractive. That only matters if you need to exit early, as you could face a capital loss. If you hold to maturity, you lock in the yield and eliminate that risk. Net: credit risk is contained; interest rate risk is the more practical consideration.






Leave a comment