
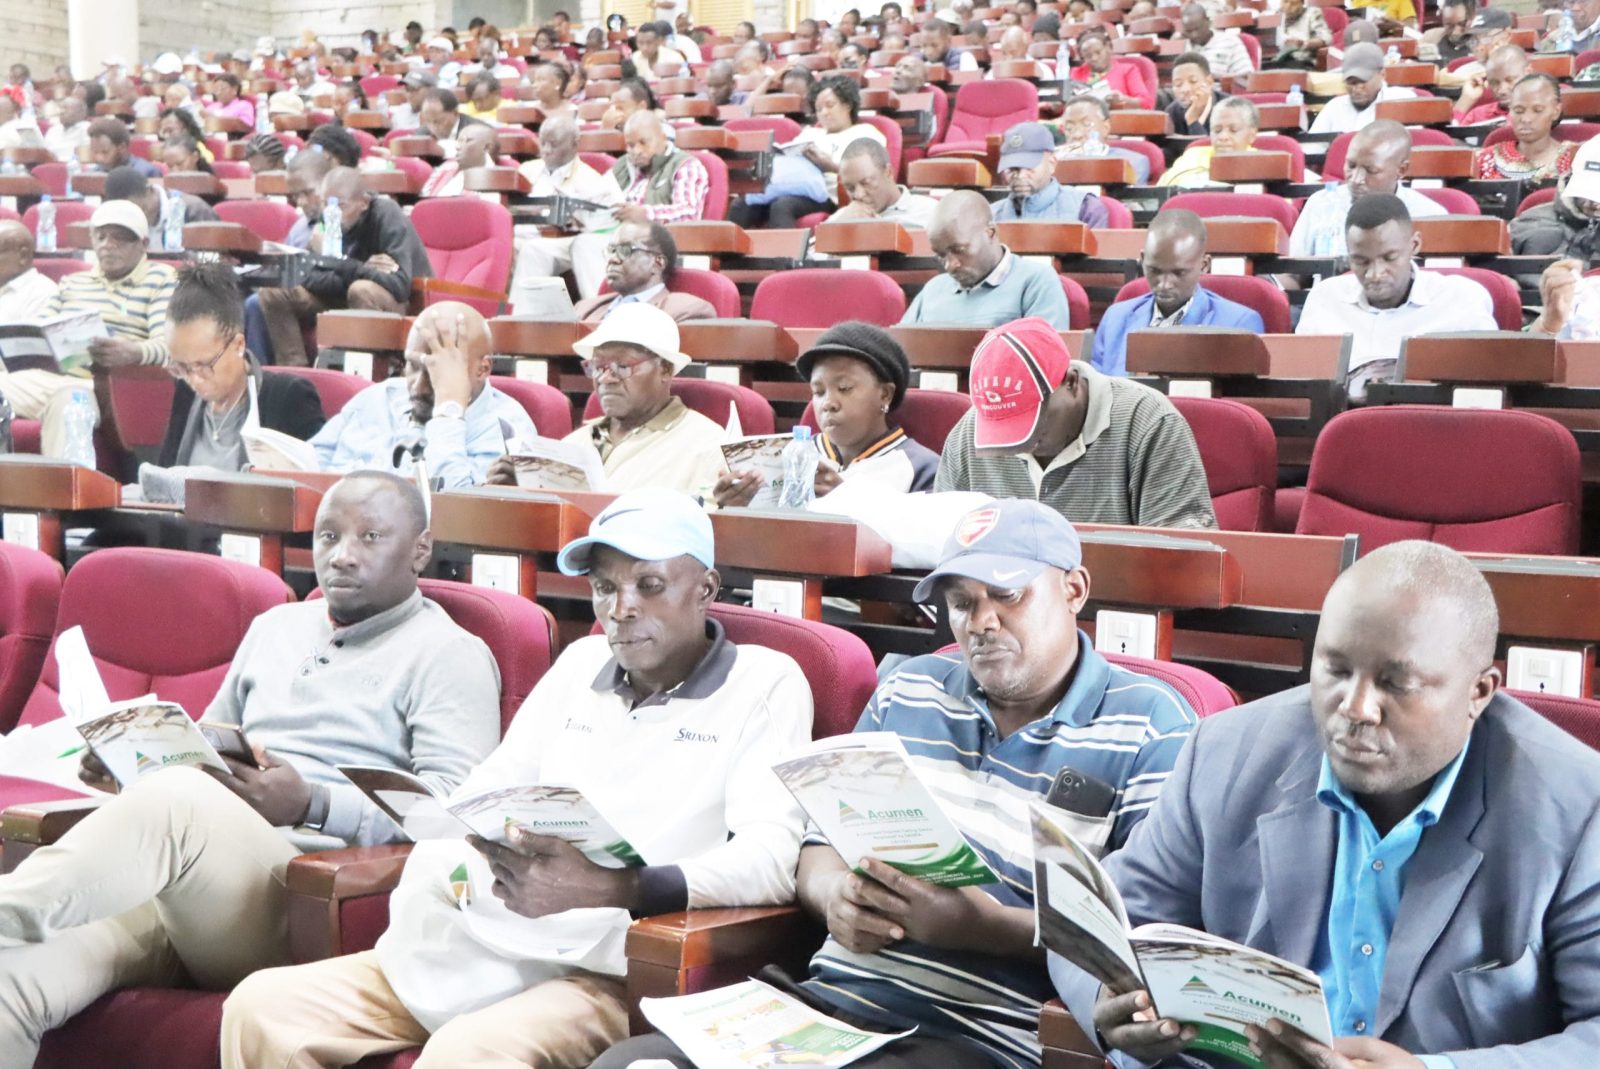
SACCOs( Savings and Credit Cooperative Societies) continue to defy the prevailing harsh economic times as the sub-sector continues to collect more deposits from members, grow their deposits and the balance sheet size.
According to the latest report from the SACCO Societies Regulatory Authority(SASRA), the total balance sheet size for all regulated SACCOs grew from KSh 1.1 trillion in June 2025 to KSh 1.2 trillion in June 2026.
The Regulated SACCO Industry Quarterly Statistical and Soundness Report, for the Second Quarter ended June 30th 2026, Gross Loans grew from KSh 881.62 billion in June 2025 to KSh971.62 billion in Q2 2026.
A large bulk of these SACCO loans were disbursed to members to enable them purchase land or put up houses. Some KSh 32.10 billion was lent out by SACCOs for members seeking to purchase land, at the end of June this year, compared to KSh 30.08 billion in Q2 2025.
SACCOs growth between June 2025 and 2026
According to the SASRA statistical report, purchase of land received the top priority on the list of members, who borrowed KSh 17.34 billion to acquire land compared to KSh 14.76 billion credit from SACCOs for purchase of housing or real estate properties. In June 2025, SACCO members spent KSh 15.93 billion to purchase land and a total of KSh 14.14 billion to acquire real estate properties.
SACCO members also borrowed to finance education of their children, to the tune of KSh 27.83 billion compared to KSh 22.26 billion in Q2 2025.
Members also accessed loans worth KSh 25.04 billion to finance various agricultural activities with Crop Farming taking up KSh 11.82 billion, Animal production (KSh 10.56 billion) from KSh 7.31 billion in Q2 2025 and Agribusiness soaking up loans worth KSh 0.93 billion down from KSh 0.95 billion in Q2 2025.
Also recording a dip is loans for Agriculture supporting services, which declined to KSh 1.27 billion compared to KSh 1.47 billion borrowed over the first six months of 2025.
In the trade sector, SACCO loans rose to KSh 19.03 billion from KSh 15.46 billion in June 2025, boosted by disbursements to the wholesale and retail segments of KSh 13.25 billion from KSh 9.95 billion in Q2 2025. Hospitality and Foreign trade segments recorded modest declines as effects of the Middle East crisis takes its toll.
Also affected were loan demands for SACCOs in the ICT business, which fell from KSh 0.85 billion in Q2 2025 to KSh 0.27 billion in Q2 2026. However, cottage and servicing industries grew their loan demands.
Loans for medical services went up from KSh 2.7 billion in Q2 2025 to KSh 3.62 billion, an indication of reliance of SACCO members on loans to finance their health needs.
SACCO members also increased their appetite for loans to purchase staple food, other consumer goods and social expenses from KSh 10.98 billion in Q2 2025 to KSh 11.26 billion at the end of second quarter of 2026.
Loans from SACCOs for investment needs increased from KSh 1.79 billion in Q2 2025 to KSh 1.91 billion at the close of June 2026.
Loans for Mortgages rose significantly from KSh 1.52 billion and doubling to KSh 3.14 billion in Q2 2026. SACCOs increased their loans to commercial banks from KSh 1.11 billion in Q2 2025 to KSh 1.61 billion in Q2 2026.
A number of SACCOs have moved to strengthen financial literacy and relationships with their members, as a way of dealing with non-performing loan as a harsh economy hits members.
What is the take from SACCO top executives?
“It is important that financial literacy programs are conducted with members and potential ones. If this is not done properly, SACCOs risks incurring loan defaults. For instance, when a member taking a business loan or an SME to increase stocks and instead diverts the monies to other uses, then loan repayment becomes a challenge and defaults are likely. Therefore, financial literacy is important and key,” said Joyce Waceke Ndegwa, Mentor SACCO Chief Executive Officer.
Mentor SACCO ensures that it provides all the necessary information before any loan is taken, walks the journey together with the borrower and provides continuous advice.
Most SACCO members usually have good plans before a loan is disbursed only for the story to change once the money and the excitement comes in.
“We see such cases and therefore engage the member before the loan is taken. We make the agreement with the owner of say, the car or piece of land on behalf of the member acquiring the asset. We ensure that the member is then able to service the loan,” said Mrs Ndegwa.
Mentor SACCO does this by encouraging members to channel all their sources of income through the SACCO so that it is able to appraise the loan applicant appropriately and offer advice.
“We encourage borrowers such as farmers who also have some rental property to channel their rental income through the SACCO, payments of their produce or for a landlord to put their rental income in the SACCO. We are then able to walk the journey together, understand you better, appraise better and advice accordingly. We will be able to grant you the monies you need based on your qualifications,” said Mrs Ndegwa.
Over the past 12 months, SACCOs disclose that the lending business has been tricky due to prevailing harsh economic conditions.
Most SACCO members are struggling to make ends meet in these challenging times. Financial challenges that most face is struggling with school fees and meeting basic needs of their families as opposed to putting money into their businesses.
Businesses are struggling
Majority of business enterprises are struggling and not doing well.
“We encourage members to take up short-term loans that they can service with the little revenues they are getting from the business. Those with salary slips are also going through hard times as their payslips shrink because of deductions that were not there previously. Their incomes have also gone down so everyone is sailing in the same ship,” said Mrs Ndegwa.
SACCOs are, however, hopeful that things will turn around for the better for members and the SACCO business.
Many SACCOs are currently restructure some loans given to businesses while giving loans to the salaried that fits the payslip. This is so members are left with some take-home to meet their financial needs after all the necessary deductions are made.
ALSO READ:CPA Joyce W. Ndegwa: How She and Her Team Built Mentor SACCO into a Thriving Business





Leave a comment