
Buying an apartment, a standalone house or a piece of land begins with a goal. And the earlier you create this goal the better. At young age in the twenties, managing a home loan would be easy since it comes with a maximum repayment window of up to 25 years, or until retirement.
Spreading payments over a longer period reduces the amount of monthly instalment, according to Mr Evan Mwangi, a mortgage specialist and real estate expert at Co-operative Bank. Even a young person earning through content production can now go all in and apply for a mortgage. This information emerged from the Co-op Bank Youth Forum, through which the bank provides financial insights to young people.
Things are even made better by the presence of Kenya Mortgage Refinancing Company (KMRC), formed eight years ago to ease mortgage financing for individuals. KMRC has over the years provided financial institutions, SACCOs and approved microfinance firms with easy to access affordable loans to on-lend to their customers.
It dishes out loans through Co-operative Bank to be used for buying ready houses, constructing homes on owned land, or buying land to build. The mortgage limits go up to Ksh10.5 million depending on location and terms. But you don’t have to borrow your maximum if all you need, is say, Ksh1.5 million, Mr Mwangi points out.
Related >> Start Planning Your Retirement at 25 years of Age
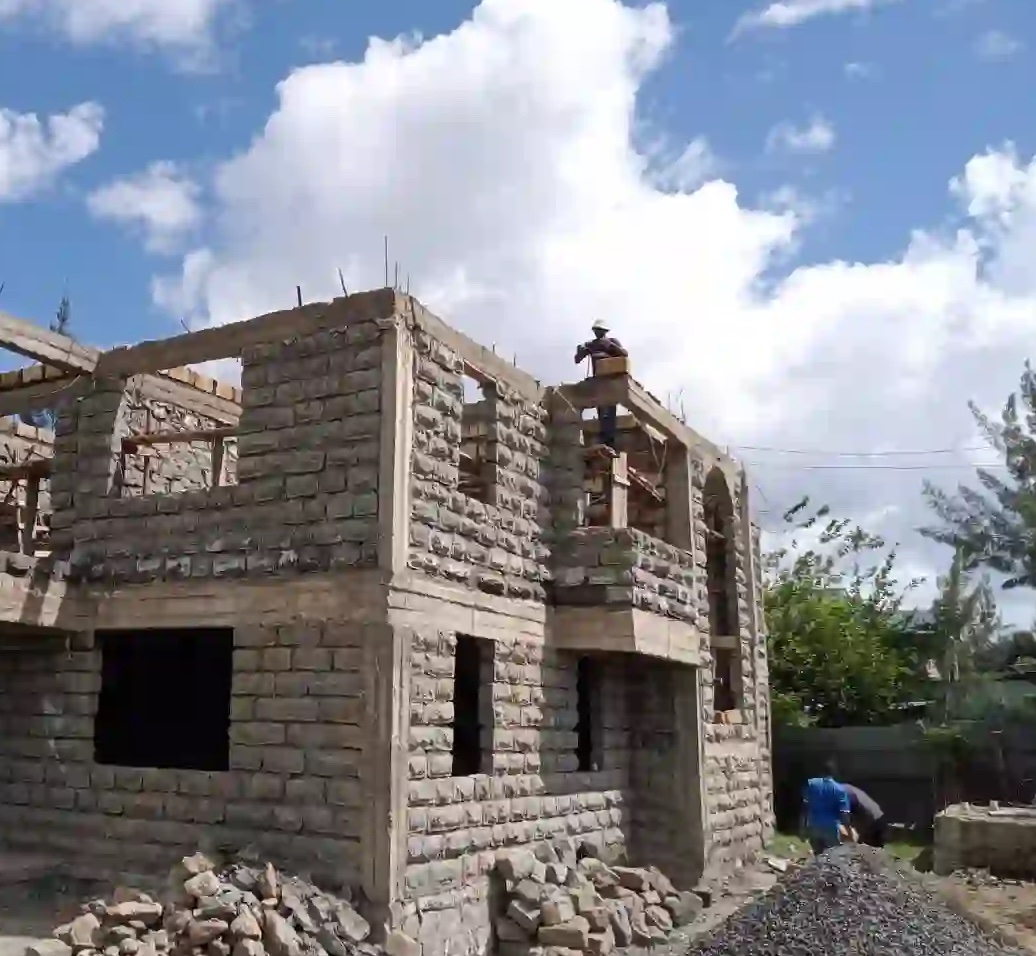
When building a house, the bank loan works in phases, which entails starting with foundation, moving to super structure and then roofing. A borrower is given about 20% of the loan amount for foundation, then the super structure, roofing, and eventually finishing. The six-month moratorium offers the much-needed relief for borrowers.
For those in business, Mwangi says you need to keep good business records to support the loan application. Co-operative Bank reviews CRB report, and net income (what you are left with as net income) after deductions.
“We will need business records to see how you have been doing the business, the invoices you send and how you are paid, which could be via mobile money like M-Pesa or bank. Those records also help you know what are your profit margins so you don’t end up taking bigger loans and regretting in the end,” Mwangi says.
It is also important to note that one cannot have more than one KMRC loans. “The thing is, one person one house. You might need to have a holiday home, but for KMRC, it is about affordable home loan… Co-op Bank KMRC loan is for buy and build,” says Mwangi.
The title of the land you are building on serves as security for the mortgage.




Leave a comment