
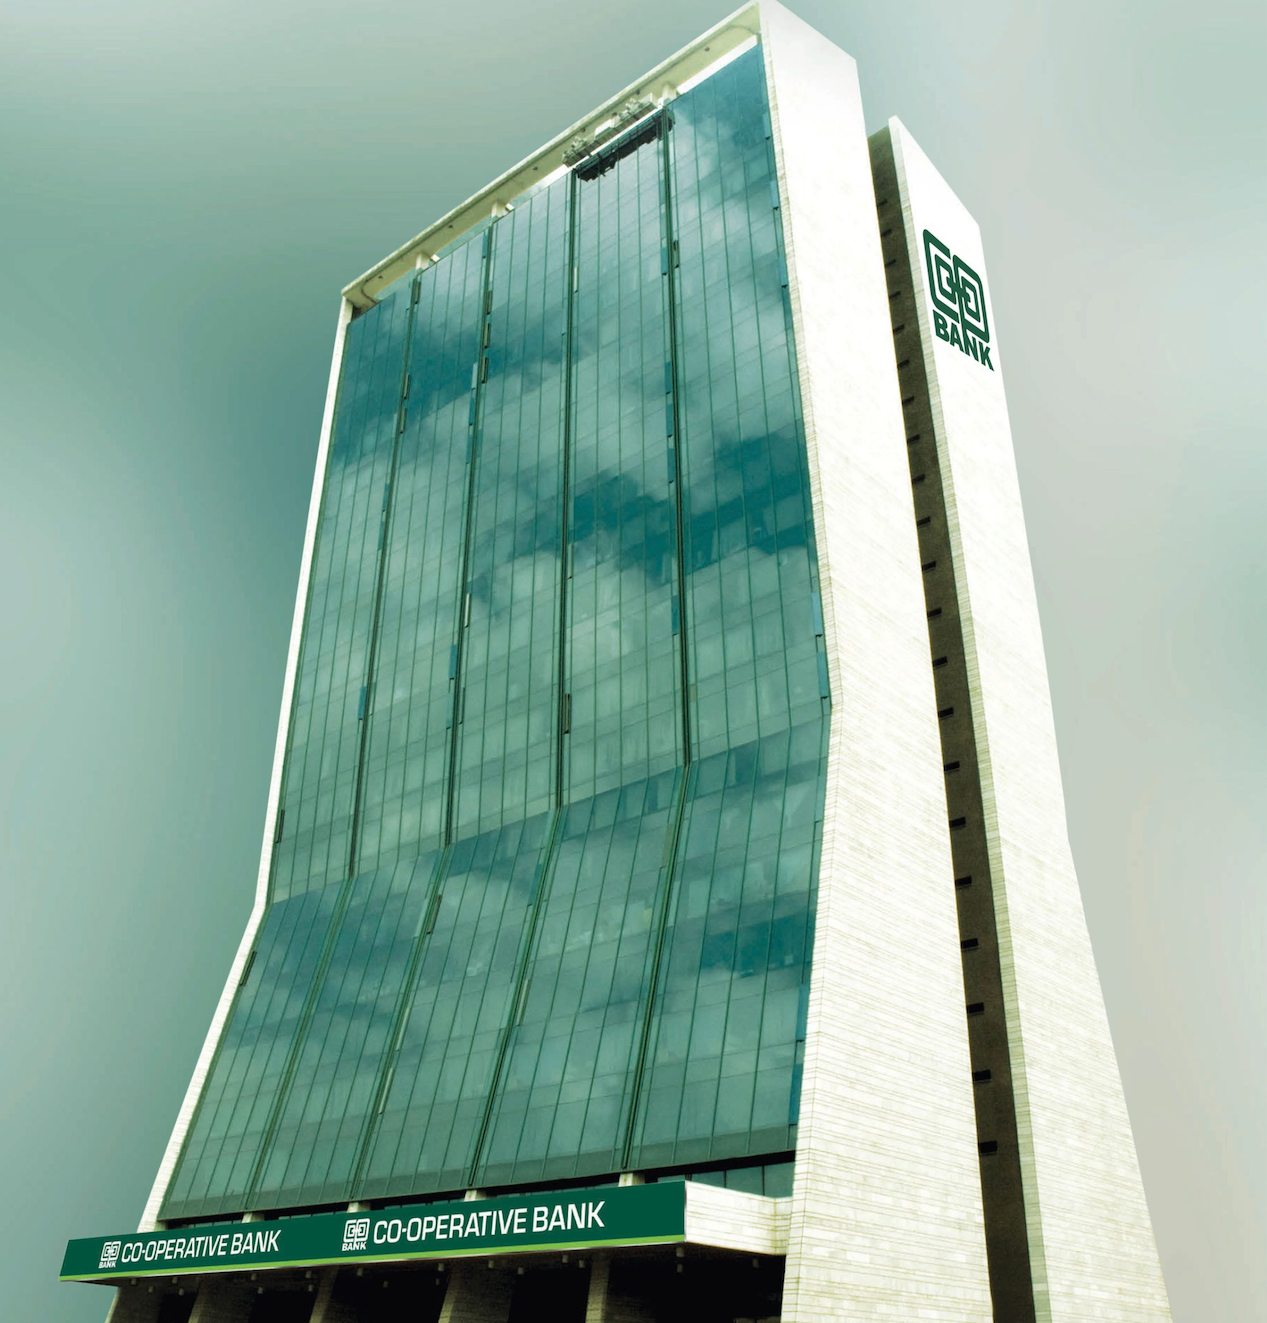
Co-op Bank Shareholders are set to share KSh8.8billion as total interim dividends payout. Book closure is 25th November 2026 and payment to shareholders on the register is set for 4th December 2026.
The biggest beneficiaries include Co-op Holdings Co-operative Society Limited with a 64.56% stake- the vehicle for Kenya’s cooperative movement that has over 15 million members.
Gideon Muriuki, CEO and Managing Director, Cooperative Bank is set to earn KSh 202.5million in interim dividends from his 2.3% stake in the bank. He is the largest individual shareholder with 135,028, 400 shares.
Aksaya Investment Holdings/Patel, Baloobhai with 1.70% stake or 100 million shares in the second largest individual shareholder.
Other beneficiaries are shareholders that have nominee accounts with local institutions owning 83.33% of Co-op Bank while foreigners own a 0.25% stake and local individuals own 16.64% of the bank.
Co-operative Bank Q3 2026 Performance.
▪️Co-operative Bank delivered a strong performance in Q3 2026, with PAT rising 27.2% Y/Y to KSh 27.4Bn, supported by robust revenue growth, reduced provisioning and improved asset quality.
▪️Balance Sheet Growth: Loans and advances grew by 22.2% to KSh 496.9Bn, while customer deposits increased 15.4% to KSh 633.0Bn.
▪️Revenue Growth: Net interest income rose by 12.7% to KSh 51.0Bn, supported by a 4.4% decline in interest expenses. Non-funded income grew 9.2% to KSh 24.1Bn.
▪️Improved Efficiency: Operating income increased by 11.6% to KSh 75.2Bn, outpacing the 5.3% growth in operating expenses to KSh 39.7Bn.
▪️Better Asset Quality: Loan loss provisions declined by 34.2% to KSh 4.8Bn, while the NPL ratio improved to 13.1% from 17.3%.
▪️Profitability: PBT grew by 19.6% to KSh 35.9Bn, with EPS increasing by 27.2% to KSh 4.68.
Co-op Bank delivered strong earnings growth, underpinned by healthy loan expansion, lower funding costs & reduced credit provisioning. The decline in the NPL ratio is particularly encouraging, although asset quality remains an area to monitor.
Co-op Bank of Kenya Asset Base
In its outlook, Standard Investment Bank(SIB) said Co-op Bank delivered an impressive performance in 3Q26, with Net Profit surging by 27.2% as execution under its “Good to Great” 2025–2029 Strategic Plan gains traction; the Group is closing in on its KSh 1.0tn asset target (currently KSh 907.4billion).
The Group’s asset quality continues to improve, with enhanced IFRS coverage (82.2% vs 70.4% in 3Q25), a softer NPL ratio (12.9% vs 17.1% in 3Q25), and lower cost of risk (1.4% vs. 2.5% in 3Q25), reducing provisioning drag.
Diversified revenue streams are anticipated to support Group earnings in the long term, on the back of an expanding loan book, deeper insurance penetration across its customer base, increased capital market activity, and growth in its fund management business (Asset Under Management at KSh 508.8bn).
While costs are expected to remain elevated in the near term as it continues to implement its expansion and digitization initiatives, Co-op is expected to benefit from efficiency gains aided by digital scale (94% alternative channel transactions) and the implementation of its enterprise-wide transformation Project Angaza, to become an AI-powered bank.
Co-op Bank aims to be the primary financial provider for the expansive co-operative movement under its vision of “One Bank, One Movement”.
While the proposed SACCO Societies (Amendment) Bill introduces potential long-term competitive dynamics as SACCOs formalize shared liquidity and guarantee frameworks, Co-op Bank’s deep integration with the SACCO industry positions it as the primary infrastructure and settlement partner.
Furthermore, the Group previously announced plans to restructure into a holding company structure, offering a platform for scalable expansion into diversified financial services and new markets in the region.
Co-operative Bank is trading at a 1.3x tangible P/B and a P/E ratio of 7.8x, a slight premium compared to the industry’s 1.2x P/B and 6.8x P/E.
Given the Group’s organic growth trajectory, captive ecosystems, diversified business lines, and a stable dividend policy, SIB recommends investors to hold the Co-op Bank Counter, with the investment bank having a fair value estimate coming in at KSh 37.22. The stock is up 72.5% year-to-date.






Leave a comment